

The ongoing conflict in the Middle East is no longer just a geopolitical crisis — it is now being felt in wardrobes around the world. From rising freight rates to rerouted shipping lanes, the war is quietly but steadily driving up clothing prices for everyday consumers, adding fresh pressure to a global fashion industry already navigating a fragile post-pandemic recovery.
Shipping Disruptions at the Heart of the Problem
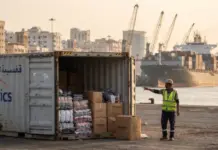
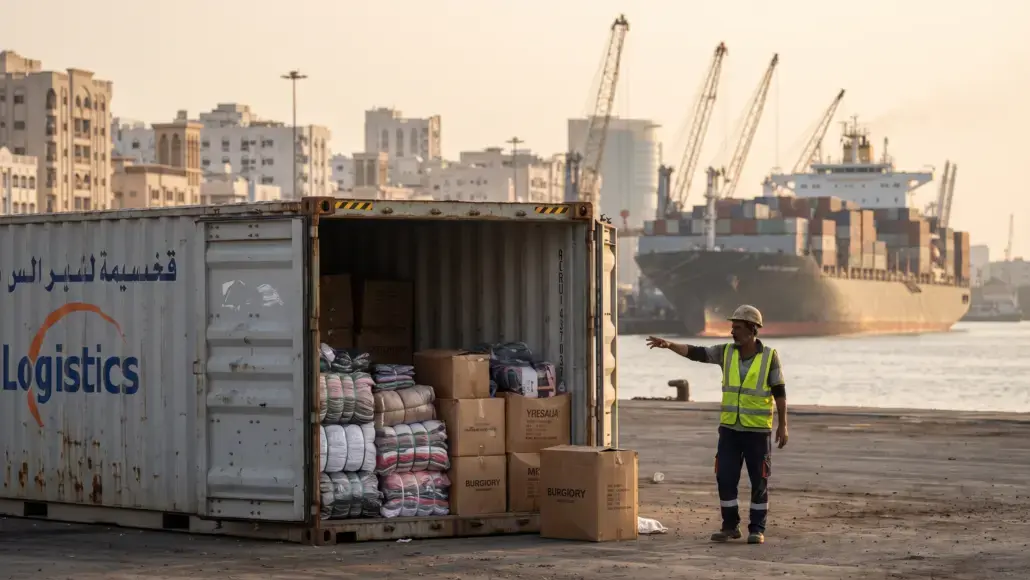
At the core of the issue is the Red Sea — one of the world’s most critical maritime corridors. A significant share of global cargo, including textiles and finished garments, typically passes through this route connecting Asian manufacturing hubs to European and American markets. The Middle East conflict has made this passage increasingly dangerous, prompting major shipping carriers to divert their vessels around the Cape of Good Hope at the southern tip of Africa.
This detour is not a minor inconvenience. It adds roughly ten to fourteen days to standard shipping journeys and substantially increases fuel consumption and operational costs. Those additional costs do not disappear — they are passed down through the supply chain and, ultimately, absorbed by the end consumer in the form of higher clothing prices.
Fashion Supply Chain Under Pressure
The fashion supply chain is particularly vulnerable to these kinds of disruptions. Unlike some industries where goods can be stockpiled or production timelines can flex with relative ease, fashion operates on tight seasonal schedules. Delays in the arrival of raw materials or finished goods can mean missed retail windows, unsold inventory at the wrong time of year, and cascading financial losses.
Freight rates, which had already surged during the pandemic years and then gradually normalized, began climbing again as the Middle East conflict intensified. Shipping costs on key Asia-to-Europe routes saw sharp increases, with some reports indicating that spot rates more than doubled compared to pre-conflict levels. For fashion businesses that depend on cost-efficient movement of large volumes of goods, these figures translate directly into margin erosion and, subsequently, retail inflation at the point of sale.
Importers and retailers have been left with limited options: absorb the additional costs, reduce order volumes, or pass the expense on to consumers. Many are doing a combination of all three, but the pressure on clothing prices remains real and ongoing.
Consumers Bearing the Cost
Shoppers in Europe and North America are beginning to notice the effects. Clothing prices, which had shown signs of stabilizing in late 2023, are once again trending upward. The Middle East war clothing dynamic is one of several contributing factors, alongside persistent inflation and currency fluctuations, but it is emerging as an increasingly significant driver.
Industry stakeholders have noted that the increases are not limited to luxury or premium segments. Mass-market and value retailers — which rely heavily on efficient, low-cost global logistics — are equally exposed. In some cases, these retailers have less pricing power to absorb costs quietly, making the impact on retail inflation more visible to budget-conscious consumers.
Rerouting and Its Broader Consequences
The decision by carriers to avoid the Red Sea and Suez Canal route has had a ripple effect across global trade, not just fashion. However, given the volume of textiles and apparel that flows through these lanes — particularly from production centers in Bangladesh, India, China, Vietnam, and Cambodia toward Western markets — the fashion industry is disproportionately affected.
Port congestion at alternative transit points has added further delays. When a large number of vessels suddenly converge on a different set of ports, waiting times increase, handling capacity becomes strained, and the efficiency gains that modern global logistics were built upon begin to erode. Each of these friction points adds incremental cost to the fashion supply chain and contributes to the upward drift in clothing prices.
No Immediate Relief in Sight
There is little indication that the situation will normalize in the near term. As long as the Middle East conflict continues to pose security risks to vessels in the Red Sea region, carriers are unlikely to resume their standard routes at scale. This means that the elevated shipping costs and extended delivery timelines are likely to persist, keeping pressure on fashion supply chain economics for the foreseeable period.
For the industry, this represents yet another test of resilience. Companies are being urged to review their sourcing strategies, consider alternative suppliers closer to their end markets, and revisit inventory planning models to better account for extended lead times. While such structural shifts take time to implement, the urgency is becoming harder to ignore as retail inflation continues to erode consumer spending power and demand becomes increasingly price-sensitive.
The message from the supply chain is clear: the Middle East war clothing cost equation has shifted, and the full weight of that shift is now making its way to store shelves and online checkouts across the world.