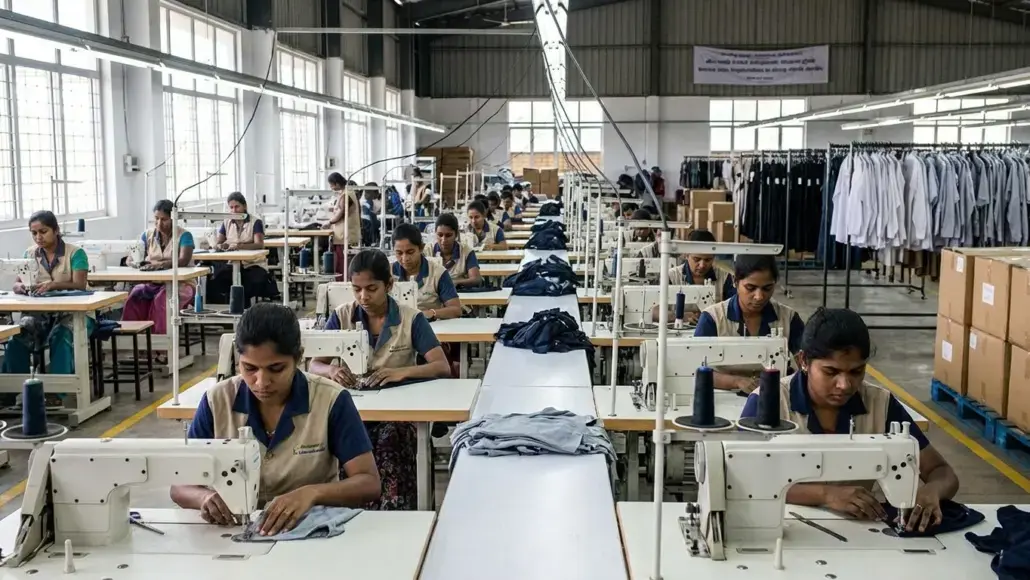
Sri Lanka’s textile and apparel sector is one of the country’s most economically vital industries, generating approximately $5 billion in annual exports and contributing more than a third of the nation’s total merchandise export earnings. The industry has now set its sights on reaching $8 billion in annual exports by 2030 — a target that aligns with the government’s broader export growth ambitions. However, achieving that figure will require far more than incremental progress.
A Sector Still Recovering From Its Own Peak
Export data tells a telling story. Sri Lanka apparel exports reached approximately $5.59 billion in 2022, before declining to $4.54 billion in 2023 and recovering partially to $4.76 billion in 2024. By 2025, exports had climbed back to around $5.02 billion, marking a return to pre-decline levels — but still well below the 2022 high. To reach the $8 billion target, the industry would need to grow its export earnings by roughly 60 per cent from current levels within the next five years.
What makes this challenge even more pronounced is the fact that the $8 billion target is not entirely new. Sri Lanka’s apparel industry had previously set the same goal — with a 2025 deadline. That target was not met, with exports remaining around the $5 billion mark throughout. The renewed 2030 ambition therefore brings with it a pointed question: what will be done differently this time around?
The Real Question Is Structural, Not Just Numerical
The arithmetic of the textile export growth target is relatively simple: add approximately $3 billion to annual export revenues over five years. The more complex question is where and how that growth will materialise. Industry stakeholders and analysts suggest that the path forward is less about broadening the geographical footprint of garment manufacturing and more about deepening the value chain.
Sri Lanka does have precedent for successfully deploying coordinated industrial policy in this sector. The 200 Garment Factories Programme, launched during the 1990s, effectively decentralised garment manufacturing beyond the capital Colombo, channelled investment into rural areas and widened the geographic base of the industry considerably. However, the nature of today’s challenge is substantially different.
Reducing Dependence on Imported Inputs
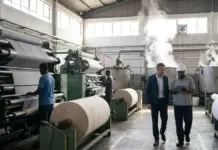
One of the most persistent structural constraints facing the apparel industry is its heavy reliance on imported raw materials — particularly fabric. Industry estimates place annual textile and apparel input imports at around $2 billion. Expanding domestic production of synthetic yarn, fabrics, trims, and packaging would strengthen local supply chains and increase domestic value addition.
That said, import substitution on its own would not be enough to close a $3 billion gap. The broader consensus among industry stakeholders is that meaningful progress requires combining greater domestic value addition with sustained growth in overall Sri Lanka apparel exports.
Productivity, Technology and Higher-Value Products
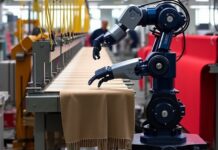
Industry leaders are placing increasing emphasis on automation, robotics, artificial intelligence, and digital production systems as tools for improving manufacturing efficiency and competitiveness. Alongside these productivity-focused measures, there is a growing push to move into higher-value market segments — including technical textiles, performance wear, and specialised products — where Sri Lankan manufacturers can compete on capability and craftsmanship rather than primarily on cost.
This shift toward higher-value production is seen as a key component of the apparel industry 2030 strategy, enabling manufacturers to generate greater revenue per unit and reduce vulnerability to cost-based competition from lower-wage economies.
Market Access as a Growth Lever
Domestic value addition and productivity improvements will only deliver results if Sri Lanka can maintain and expand its access to major export markets. Preferential market access remains a critical factor in the industry’s global competitiveness.
Recent changes to the United Kingdom’s Developing Countries Trading Scheme are one example of how policy shifts in importing countries can directly affect Sri Lankan manufacturers. The revised rules of origin under the scheme could potentially give Sri Lankan apparel exporters greater flexibility in sourcing inputs, while still retaining preferential access to the UK market — an important consideration as the industry seeks to diversify and grow.
JAAF’s Policy Calls
The Joint Apparel Association Forum (JAAF) has reportedly called for a comprehensive policy response to support the industry’s ambitions. This includes stronger investment incentives for upstream textile manufacturing, improved preferential market access, and better coordination among the institutions involved in the development of the textile and apparel sector. These calls reflect a broader recognition that reaching the $8 billion mark will require concerted effort across government, industry, and trade policy.
What Needs to Happen
The path to $8 billion in Sri Lanka apparel exports by 2030 is defined by several interconnected priorities. Industry stakeholders argue that the country must deepen its domestic supply chain, raise manufacturing productivity, increase value addition at each stage of production, develop higher-value product categories, and secure expanded opportunities in both existing and new markets.
Each of these elements individually contributes to apparel industry 2030 readiness. Together, they form the foundation of what would need to be a coordinated and sustained push to add $3 billion to annual export earnings — within a five-year window that has already begun.
Whether the industry can deliver on the 2030 target where it fell short of the 2025 one will depend on whether the structural reforms, investment incentives, and market strategies now being discussed translate into measurable action on the ground.