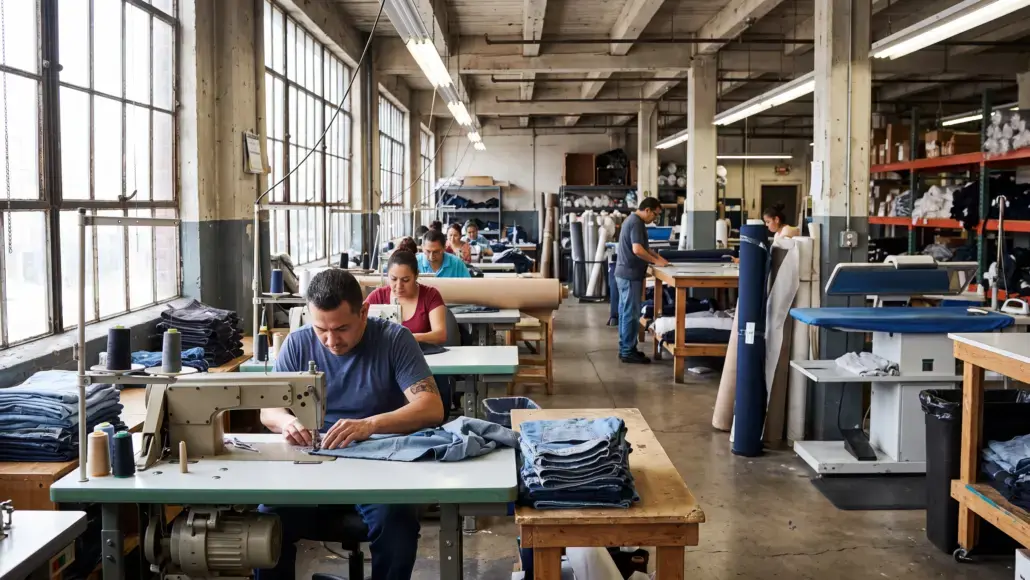
US apparel original equipment manufacturing (OEM) and original design manufacturing (ODM) companies are seeing stronger business activity even as American consumer confidence remains weak. The improvement is being linked less to a broad recovery in clothing demand and more to how international fashion companies are restructuring sourcing amid tariffs and geopolitical uncertainty.
The University of Michigan’s preliminary September consumer sentiment index stood at 47.8, which would rank among its weakest readings. However, spending has remained relatively resilient, with US retail sales increasing 1.2% month on month in August, according to Reuters.
Against this backdrop, fashion companies are increasingly concentrating sourcing among larger suppliers capable of operating production facilities in several countries.
A survey conducted by the United States Fashion Industry Association and the University of Delaware found that 47.4% of 30 major US fashion companies surveyed between April and June planned to reduce their apparel supplier base over the following two years. The proportion was significantly higher than the 17.6% recorded in the previous year.
At the same time, the percentage planning to expand their supplier networks fell to 26.3% from 41.2%. Companies intending to increase the number of production countries also declined sharply, from 58.8% to 21.1%.
The change indicates a move towards more consolidated sourcing structures. Large vendors with manufacturing operations spread across Vietnam, Bangladesh and Central and South America can shift production between locations as tariff rates, labour expenses and logistics conditions change.
This model is supporting the performance of major Korean apparel suppliers. Youngone, Hansae and Shinwon all reported higher sales and operating profits during the second quarter.
Youngone posted second-quarter sales of KRW 1.23 trillion and operating profit of KRW 175.6 billion, representing increases of 19% and 20%, respectively. OEM revenue climbed 22% to KRW 850.1 billion, while OEM operating profit increased 18% to KRW 198.7 billion.
Youngone’s first-half OEM sales increased 12% in dollar terms, according to NH Investment & Securities. Sales to The North Face rose 12%, while Arc’teryx sales jumped 58%. Revenue from other customers outside its four largest accounts increased 19%.
OEM inventories reached a record KRW 820.6 billion at the end of the second quarter, up 21% year on year, as higher orders contributed to increased materials, supplies and work in progress.
Jeong Ji-yoon, an analyst at NH Investment & Securities, said, “Youngone’s growth drivers are the consolidation of global OEM vendors, strength in sports and outdoor brands, and diversification of production bases due to the deepening U.S.-China trade dispute,” adding, “Solid sales growth is expected to continue in the second half.”
Hansae, whose US market accounts for about 90% of revenue, reported an 18.2% increase in second-quarter sales to KRW 561.6 billion. Operating profit surged 193% to KRW 36.1 billion, supported by stronger order volumes and a greater contribution from premium brands.
With manufacturing facilities in eight countries, Hansae is also expanding vertical integration covering fabric production, dyeing, spinning and sewing.
Lee Jin-hyup, an analyst at Hanwha Investment & Securities, said, “Starting with last quarter’s results, volume-driven growth is emerging. We expect volume-driven growth to continue in the second half,” adding, “It is time to watch whether we have entered an inflection point for improvement in OEM industry conditions, such as easing tariff uncertainty, or whether this is a temporary recovery.”
Shinwon, which supplies around 20 buyers including Gap and Walmart from nine overseas production bases, recorded an 11% increase in export sales and a 217% rise in operating profit during the quarter.
The performance suggests that US apparel OEM demand is increasingly influenced by supply-chain resilience rather than consumer sentiment alone. For fashion companies, fewer but larger sourcing partners can provide greater flexibility when trade policies or production economics change.
An industry official said, “In the past, low labor costs were the key competitiveness of apparel vendors, but recently the ability to quickly switch production countries in response to tariff and supply-chain uncertainty, and production capabilities that can handle everything from materials and fabrics to finished goods, are determining order wins.”
The shift could continue to reshape sourcing strategies as brands place greater emphasis on multi-country manufacturing, integrated production capabilities and the ability to respond quickly to changing trade conditions. This is strengthening the role of large-scale US apparel OEM demand suppliers even without a broad-based recovery in US consumer sentiment.