Pakistan’s textile and apparel exports remained broadly stable at approximately $18 billion in FY26, but a dramatic collapse in domestic cotton production is casting a long shadow over the sector’s future competitiveness. The Pakistan Textile Council (PTC) has flagged the situation as a growing structural risk that could undermine the export sector’s long-term performance.
According to the PTC’s annual export performance report, Pakistan textile exports reached $18.004 billion in FY26, reflecting a marginal increase of just 0.3% from $17.95 billion recorded in FY25. The near-stagnant growth comes against a broader backdrop of strain, as Pakistan’s overall exports fell 5.9% to $30.14 billion during the same period.
Cotton Production Hits a Three-Decade Low
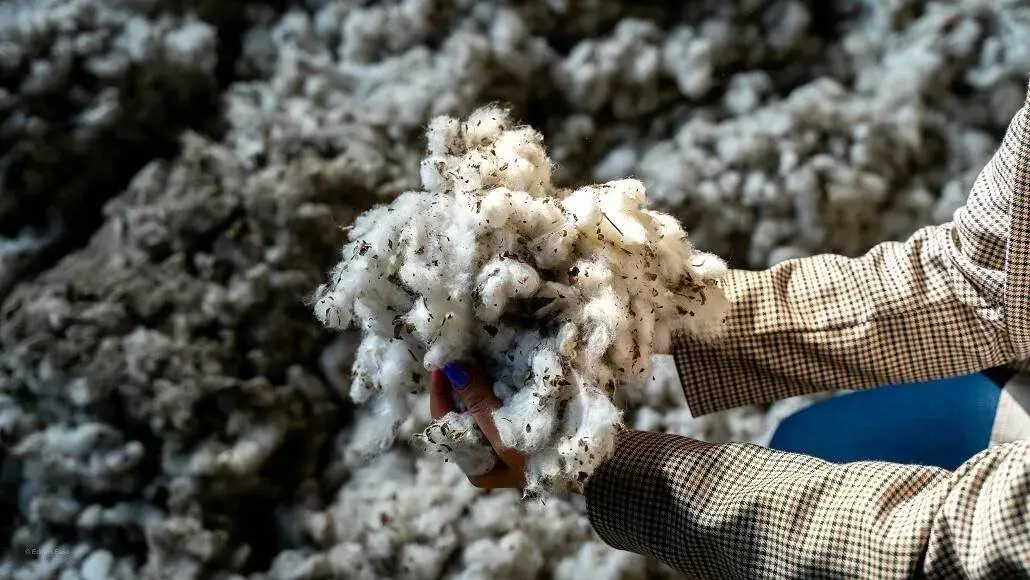
The most pressing concern flagged by the PTC relates to domestic cotton output, which dropped to 5.5 million bales in the latest season — the lowest production level in thirty years. At its peak in 2011-12, Pakistan produced a record 14.8 million bales, meaning current output represents a decline of nearly 70% from that high point.
The council attributed the latest fall to extreme heat during the June-July flowering period, along with severe water shortages in Sindh and southern Punjab. As domestic cotton supplies continue to shrink, textile manufacturers are increasingly turning to imported raw materials, a shift that is raising production costs and threatening the price competitiveness of Pakistan’s export-oriented textile industry.
Raw Material Exports Under Pressure
The pressure is already visible in export data. Exports of raw materials and intermediate textile products fell 3.4% to $3.026 billion in FY26, marking the lowest figure in five years when compared to $4.498 billion in FY22. Cotton accounted for more than 80% of this category, yet cotton exports themselves slipped 1.5% to $2.486 billion.
The cotton production decline has had a cascading effect across related segments. Exports of man-made staple fibres dropped 8.8%, while man-made filament exports fell a sharper 26.2%. Knitted fabric exports declined 20.7%, further underlining the stress building within the textile supply chain.
Value-Added Segment Provides a Buffer
While upstream segments struggled, Pakistan’s textile industry continued its shift toward higher-value products. Exports under the finished and value-added categories increased 1.1% to $14.979 billion in FY26. These products now represent 83.2% of total Pakistan textile exports, up from a 77% share in FY22.
Non-knit apparel delivered the strongest growth among major value-added categories, with exports rising 3.9% to $4.295 billion. Made-up textile articles also grew, increasing 0.6% to $5.705 billion. However, knitwear exports edged down 0.7% to $4.979 billion, adding a note of caution even within the higher-value segment.
The PTC has been clear in its assessment: growth in value-added exports is currently masking deeper weaknesses within the textile supply chain. Securing adequate raw material at competitive costs remains a challenge the industry cannot afford to ignore.
Key Market Performance
The United States remained Pakistan’s largest individual growth market. Textile exports to the US grew to $4.853 billion from $4.768 billion in the prior year. Exports to China also increased, reaching $644 million compared with $527 million a year earlier.
The European Union remained the largest textile market overall for Pakistan, though exports to the bloc declined to $7.103 billion from $7.248 billion. Exports to the United Kingdom also dipped slightly, falling to $1.730 billion from $1.749 billion.
Rising Costs and a Difficult Close to FY26
Beyond the cotton production decline, the Pakistan export sector is grappling with a range of logistical and financial pressures. Longer transit times, higher freight charges, expensive energy, costly financing, and taxation burdens continue to weigh on exporters. These pressures intensified sharply towards the end of the fiscal year. Pakistan textile exports fell 17% year-on-year to $1.27 billion in June 2026, compared to $1.53 billion in June 2025, and declined 23% from May’s $1.65 billion.
The Road Ahead: PTC’s Proposed Strategy
To address these compounding challenges, the PTC has called for a comprehensive national cotton strategy. The proposed plan would focus on improving seed quality, advancing farmer digitisation, and strengthening supply-chain traceability. The council has also urged the government to reduce energy and financing costs, accelerate tax refund processing, and improve export logistics infrastructure.
As Pakistan enters FY27, the structural challenges facing the textile sector are difficult to overlook. Textiles account for roughly 60% of the country’s total merchandise exports. Continued declines in domestic cotton output could push production costs higher and weigh on the sector’s long-term export growth trajectory — making the resolution of the raw material crisis one of the most urgent priorities for industry and policymakers alike.